For Institutions
Understand what you are offering. Help the people relying on it understand it too.
Independent buyer-side diligence for institutions evaluating long-term financial products.
Longevity Standard helps institutions examine what a product promises, what can change, what may affect delivery, and what the evidence actually supports, then turn that work into clearer understanding for the people who may ultimately rely on it.
One body of work
Independent diligence for the institution. Clearer understanding for the end user.
For the institution
A structured view of the product, the evidence, important dependencies, and unresolved questions.
For participants or customers
A clearer explanation of what the product does, what can change, what matters over time, and where to look for more detail.
The end-user explanation is derived from the same independent investigation that supports the institutional diligence.
When it’s useful
Before, during, and after a product is offered.
Before you pay
01
Before adoption
Independently examine a proposed product before it is placed in front of participants or customers.
Before you pay
02
During implementation
Translate the underlying diligence into clearer participant- or customer-facing explanation.
Before you pay
03
When something changes
Revisit important terms, rates, riders, issuer conditions, or other material facts.
Before you pay
04
During ongoing oversight
Maintain a current understanding of what the institution continues to offer.
Before you pay
05
When questions arise
Provide an independent evidence base for a committee, adviser, participant, or customer.
A product can be approved long before its long-term value is known.
What is often harder to see is how the economics fit together over time.
Which values are actually usable?
Which assumptions or conditions have the biggest effect on the value that is ultimately delivered?
What may matter years after the original decision?
Independent by design
Independent analysis focused on the institution and the people relying on the product.
Longevity Standard provides buyer-side diligence, with economics tied to doing the analysis rather than to which product is selected, how much is purchased, or whether a transaction takes place. That creates a different starting point for evaluating long-term financial products.
LS Review — product screen
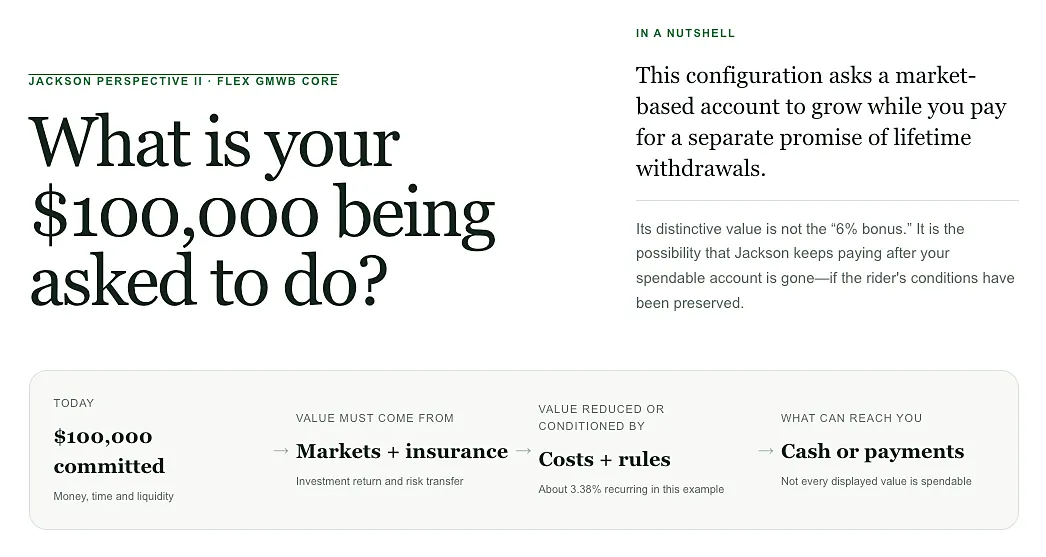
Fig. 02
The analysis itself — what the economics are tied to
Research infrastructure
Build on a structured evidence base.
Longevity Standard maintains structured, source-linked research on financial institutions and the products they issue.
LS Review — issuer record, detail
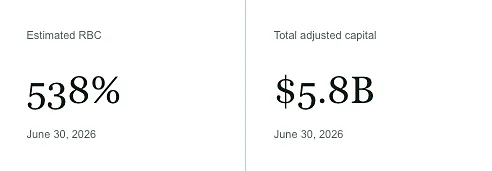
Fig. 01
A dated observation, held against its source
What the base holds
Legal entities and ownership relationships
Product forms and versions
Relevant terms and riders
Dated observations and events
Source documents
Other evidence needed to understand the product in context
Specific plan, participant, or customer materials can then be matched against that broader research base where applicability matters.
The method
Follow the product from commitment to delivery.
01
What is being promised?
02
What does the end user give up?
03
What can reduce or constrain value?
04
What can change?
05
What conditions matter?
06
Who is responsible for delivery?
07
What does the evidence establish?
The goal is not more information. It is better institutional understanding with traceable evidence behind it.
From diligence to explanation
Explanation should come from investigation.
Longevity Standard starts by establishing what the product actually does and what the evidence supports. That same underlying work can then produce a much simpler participant- or customer-facing explanation.
The diligence
Legal entities and ownership relationships
Product forms and versions
Relevant terms and riders
Dated observations and events
Source documents
The explanation
What the product does, what can change, what matters over time, and where to look for more detail.
The explanation is derived from the diligence, not created separately from it.
Over time
The product may stay in place while the facts around it change.
Long-term products may contain adjustable terms, refreshed rates, evolving source documents, issuer changes, or other developments that matter after adoption.
Over time, Longevity Standard is designed to support periodic or event-driven review of those changes.
Built for institutions responsible for evaluating, offering, or explaining long-term financial products.
Plan sponsors and benefits committees
Benefits teams
Retirement-plan consultants
Recordkeepers and platforms
Advisers and case desks
Other organizations responsible for product evaluation or oversight
The initial focus is retirement-plan lifetime income.
Start with the product in front of you.
An engagement can begin with a proposed product, an existing plan option, a participant offering, or a specific question about something already in place.
How it runs
01
Establish the relevant evidence base
02
Examine the product
03
Determine the appropriate output
From focused diligence to participant-facing explanation or ongoing oversight.
Before you place institutional credibility behind a long-term financial product, understand it.
Make sure the people relying on it can understand it too.